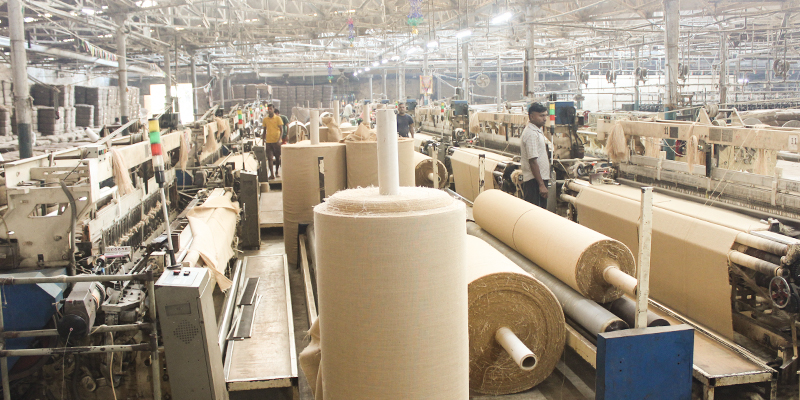
India’s jute industry is poised for a meaningful turnaround this fiscal after weathering two difficult years marked by weak demand, elevated raw material costs and pressure on profitability. A revival in domestic demand, improving export prospects and softer raw jute prices are expected to restore growth momentum, strengthen profitability and support the industry’s credit profiles.
Sales volumes are expected to grow ~15% this fiscal after declining at an annualised ~10% over the previous two fiscals, driven by stronger demand and a more favourable cost environment. An analysis of jute manufacturers we rate, which account for ~40% of industry revenue, indicates as much.
The domestic market, which contributes nearly 85% of industry revenue, remains the cornerstone of growth. Domestic demand is projected to increase about 20% this fiscal, reversing a similar cumulative decline over the preceding two years. The downturn was largely triggered by a sharp rise in raw jute prices, which manufacturers passed on to customers, dampening demand and prompting a shift towards lower-cost alternative packaging materials. With input costs now moderating, product prices are expected to soften, supporting a recovery in demand.
Export demand is also beginning to show signs of improvement. Growth in downstream sectors such as home textiles, lifestyle products and other value-added jute applications is expected to support exports. In addition, the rationalisation of US tariffs from the elevated levels seen last fiscal could improve the competitiveness of Indian jute products in global markets.
Says Rahul Guha, Senior Director, Crisil Ratings, “While improving demand will support revenue growth, profitability is likely to receive an even larger boost from easing raw material costs. Better crop output has improved domestic availability of raw jute and led to softer prices despite subdued imports. This is significant because raw jute accounts for 60-65% of the industry’s operating expenses. Lower fibre costs and improved capacity utilisation should drive up profitability. Consequently, operating margins are projected to expand by ~130 basis points (bps) to nearly 9% this fiscal.”
Raw jute prices had risen by more than 10% last fiscal because of supply constraints. However, higher minimum support prices encouraged farmers to increase acreage under cultivation, resulting in better crop output this year.
The expected improvement in profitability this fiscal, combined with limited debt-funded capex, should strengthen credit metrics. Healthy cash accruals are likely to enable manufacturers to comfortably fund maintenance capex and working capital requirements while maintaining adequate liquidity. Notably, most players have avoided aggressive debt-funded expansion over the years, favouring incremental modernisation and operational efficiency initiatives.
As a result, balance sheets are expected to remain resilient. Gearing is projected to improve marginally to about 0.5 time this fiscal from 0.6 time last year, while interest coverage is expected to strengthen to nearly 5 times from about 4 times. Improved cash generation should support stable credit profiles across the sector.
Says Argha Chanda, Director, Crisil Ratings, “Beyond the cyclical recovery, the industry stands to benefit from structural shifts towards sustainable materials. Growing environmental awareness, tighter rules on single-use plastics and rising preference for biodegradable alternatives are creating new opportunities for jute-based products. Emerging applications in geotextiles, agro-textiles, home décor, industrial packaging and other valueadded segments are gradually expanding the addressable market. While value-added applications currently account for only 12% of revenue, they offer better realisations and could become important drivers of long-term growth.”
But the recovery is not without risks. The pace and sustainability of the demand revival, particularly in export markets, will remain critical. Equally important will be the trajectory of raw jute prices, as any sharp increase could once again pressure margins. Crop-related disruptions and changes in government policy support could also influence industry performance.